Charting Transaction Pathways in UK Mobile Casino Platforms
Bianca Butler · Aug 22, 2026

Charting Transaction Pathways in UK Mobile Casino Platforms
Users begin the process by selecting a funding option within the app interface, where options range from debit cards and e-wallets to bank transfers and prepaid vouchers, each carrying distinct processing timelines and fee structures that operators must disclose upfront according to data from industry reports.
Initial Funding Steps and Platform Integration
Once a player opens the mobile application, the deposit screen presents available methods with real-time balance updates, and systems route the transaction through secure payment gateways that encrypt details before they reach financial processors, while compliance checks run in the background to flag any irregularities based on transaction patterns observed across networks.
Payment providers handle the transfer, and funds appear in the account balance within seconds for instant methods or up to several business days for traditional bank routes, a distinction that becomes clear when users compare processing speeds listed in platform terms, and observers note that volume spikes often occur during evening hours when mobile usage peaks.
Account Verification Procedures
Before full access unlocks, platforms require identity confirmation through document uploads such as government-issued photo IDs and proof of address, steps that align with broader standards set by regulatory bodies in various regions including the Gambling Regulatory Authority of Ireland, where similar verification timelines apply to online operators. This phase typically spans one to three days, during which support teams review submissions and request additional information if discrepancies arise, ensuring the account holder matches the payment source to prevent mismatches that could delay later stages.
Fund Management During Active Play
After verification clears, deposited amounts integrate into the wallet system, allowing seamless transitions between game selections without separate transfers for each session, and tracking tools display real-time deductions alongside win additions that reflect in the balance immediately upon round completion. Bonuses attached to deposits carry wagering requirements that software monitors automatically, converting eligible amounts into withdrawable cash only after conditions meet thresholds documented in player histories.
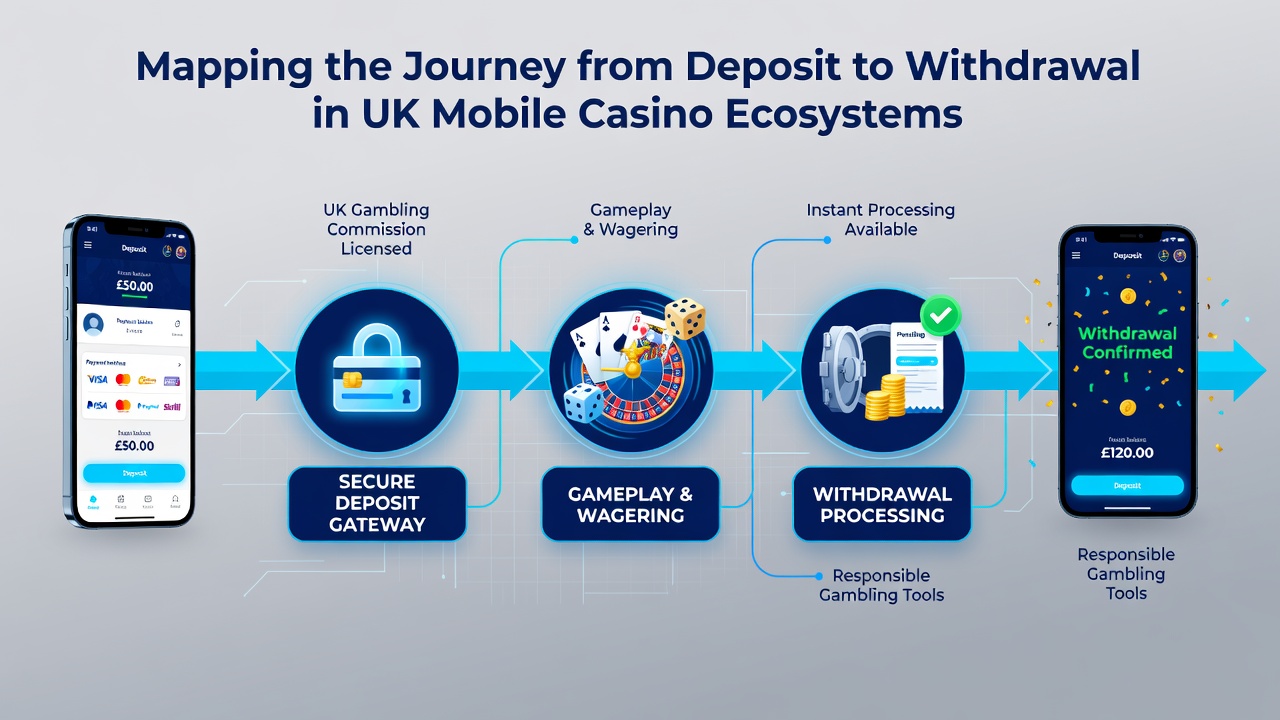
Players monitor these balances through dashboard views that update continuously, and data from transaction logs help identify patterns such as frequent small deposits versus larger single inflows, information that platforms use to tailor responsible gaming prompts without interrupting the flow of play.
Requesting and Processing Withdrawals
When users decide to cash out, they navigate to the withdrawal section, choose from pre-verified methods that often mirror deposit options, and enter the desired amount, triggering an automated review that cross-checks against play history and any pending bonuses. Processing begins once approval grants, with e-wallet transfers completing in hours while bank methods extend to three to five days, timelines that research from the University of Nevada Las Vegas International Gaming Institute indicates vary by provider infrastructure and peak load periods.
Platforms send confirmation notifications at each stage, from request receipt through final transfer, and users receive references for tracking that link back to original deposit sources to maintain audit trails. In August 2026, several UK-based operators expanded support for instant payout features tied to newer digital wallet partnerships, reflecting shifts in mobile payment adoption rates reported across European markets.
Security Measures and Common Flow Disruptions
Encryption protocols and two-factor authentication protect every transfer point, while monitoring algorithms detect unusual activity such as rapid deposit-withdrawal cycles that may prompt temporary holds until clarification occurs. Those who've studied transaction data across platforms observe that most disruptions stem from mismatched verification details rather than technical failures, and resolution involves direct communication with support teams who guide users through resubmission steps.
Regional differences in banking partner availability can influence speed, particularly for international cards, yet operators standardize reporting to keep users informed without requiring external inquiries in most cases.
Conclusion
The complete cycle from initial deposit to final withdrawal forms a closed loop supported by integrated software, verification layers, and payment networks that operate under consistent security frameworks. Tracking each phase reveals dependencies on method choice, account status, and external provider performance, elements that collectively define the operational rhythm of these mobile environments.